Underwriting support for banks, credit unions and SBA lenders, and independent quality of earnings for transactions. The work is done from the borrower’s own records, the general ledger, the bank statements, the payroll reports, the notes and the agings, and every report is signed by Philip A. Baratelli, Owner, Baratelli Transaction Advisory, LLC.
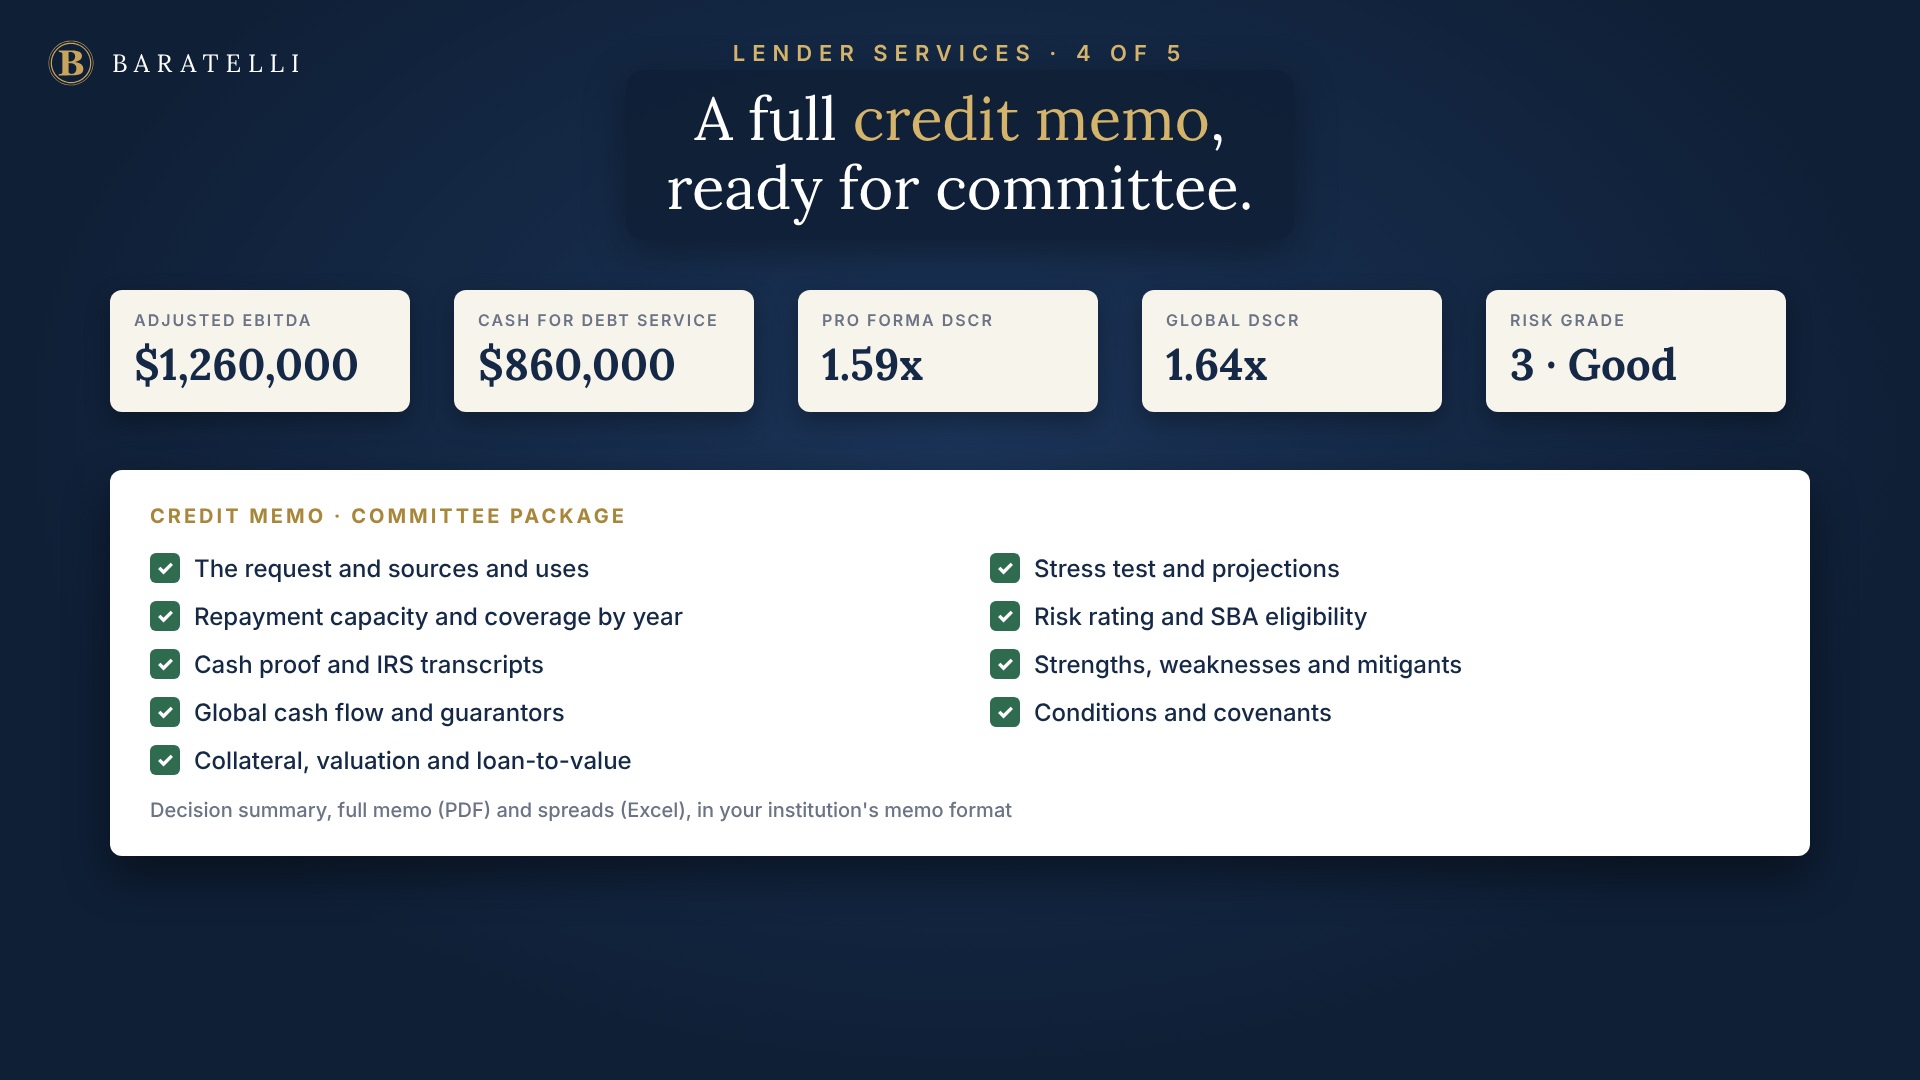
What a lender receives from the desk. Sample data; every name is invented.
Three fiscal years and a trailing twelve months, spread from the general ledger, with every adjustment traced to its document.
Existing debt read off the actual notes, the new payment at your terms, every add-back tested, and a sensitivity on revenue and rate.
Eligibility, size, use of proceeds, equity injection and change-of-ownership conditions read against SOP 50 10 8.1, with each exception cited.
The 7(a) package assembled and tied out, with every figure traced to the schedule it comes from.
Certificates verified against the agings and the ledger, ineligibles applied as the loan agreement defines them, availability recomputed.
Each covenant tested as written in the agreement, period by period, with the computation shown and the cushion stated.
Existing files graded on one rubric: what is missing, what is stale, and what would not support the credit if examined today.
Bank receipts and disbursements reconciled to the books, every add-back tested against the general ledger rather than accepted, wages tied to Forms W-3, working capital measured against a normal level, and the debt-like items the price should carry.
Under SBA SOP 50 10 8.1, in force since October 1, 2026, an Initial Acquisition or Business Expansion with a Business Purchase Price of $3 million or more (owner-occupied real estate excluded at its appraised value; Owner Buyout and ESOP & Cooperative transactions exempt) needs a quality of earnings in addition to the business valuation, performed for the benefit of the lender, with a cash proof of receipts and disbursements (Appendix 15, A.15 and C.1.i). A report prepared by or for the seller does not qualify, and the lender uses the QoE earnings in the debt service coverage.
SOP 50 10 8.1, published September 25, 2026 and effective October 1, 2026, Appendix 15. Verify the current SOP for any specific file.
A credit department with more files than capacity, or an SBA department that needs the SOP read closely. Start with the write-up and the coverage recomputation on one live file.
The earnings behind the price, before signing: add-backs tested, receipts and disbursements reconciled to the bank statements, working capital measured against a normal level.
A sell-side QoE before going to market finds the issues while there is still time to fix them; a lender cannot rely on it for SBA purposes. Start with the free sale readiness check.
Bondable: contractor books kept bond-ready
Sureties look at a contractor the way a lender looks at a borrower. Bondable keeps small and growing contractors’ books bond-ready every month: job costing, a current work-in-progress schedule, reconciliations, receivables and payables aging with retainage, and monthly financial statements with plain-language notes. It’s built for contractors whose bond programs accept company-prepared financial statements.
Lender-ordered quality of earnings, QoE reviews, cash and transcript checks, spreads and credit packages.
Download the one-page summaryA triage memo on each new business application: pursue, fix first or decline.
Download the one-page summaryReadiness checks, QoE reviews during the deal and sell-side QoE reports.
Download the one-page summarySummaries for every kind of partner are on our partners page.
Baratelli Transaction Advisory, LLC
700 S Rosemary Avenue, Suite 204
West Palm Beach, Florida 33401